Zevonix Business Suite | All-in-one Operations Manager Platform
A purchase order should not wait three days because one manager is on a job site. At the same time, a technician should not be able to approve a vendor bill, release payment, and change the bank details attached to it. Approval roles solve both problems when they are designed around real operating risk rather than job titles alone.
For small and mid-sized businesses, the goal is not to recreate enterprise bureaucracy. It is to put the right review in front of the transactions, commitments, and changes that can affect cash, margin, inventory, customer commitments, and compliance. When approval rules live in email threads, spreadsheets, and verbal instructions, control breaks down fast. Work gets delayed, decisions cannot be traced, and no one is certain who owns the next step.
Why Approval Roles Need More Than a Manager List
Many businesses start with a simple rule: managers approve everything. That works until the manager becomes the operational bottleneck. It also creates weak controls when the same person can request, approve, receive, and pay for a purchase.
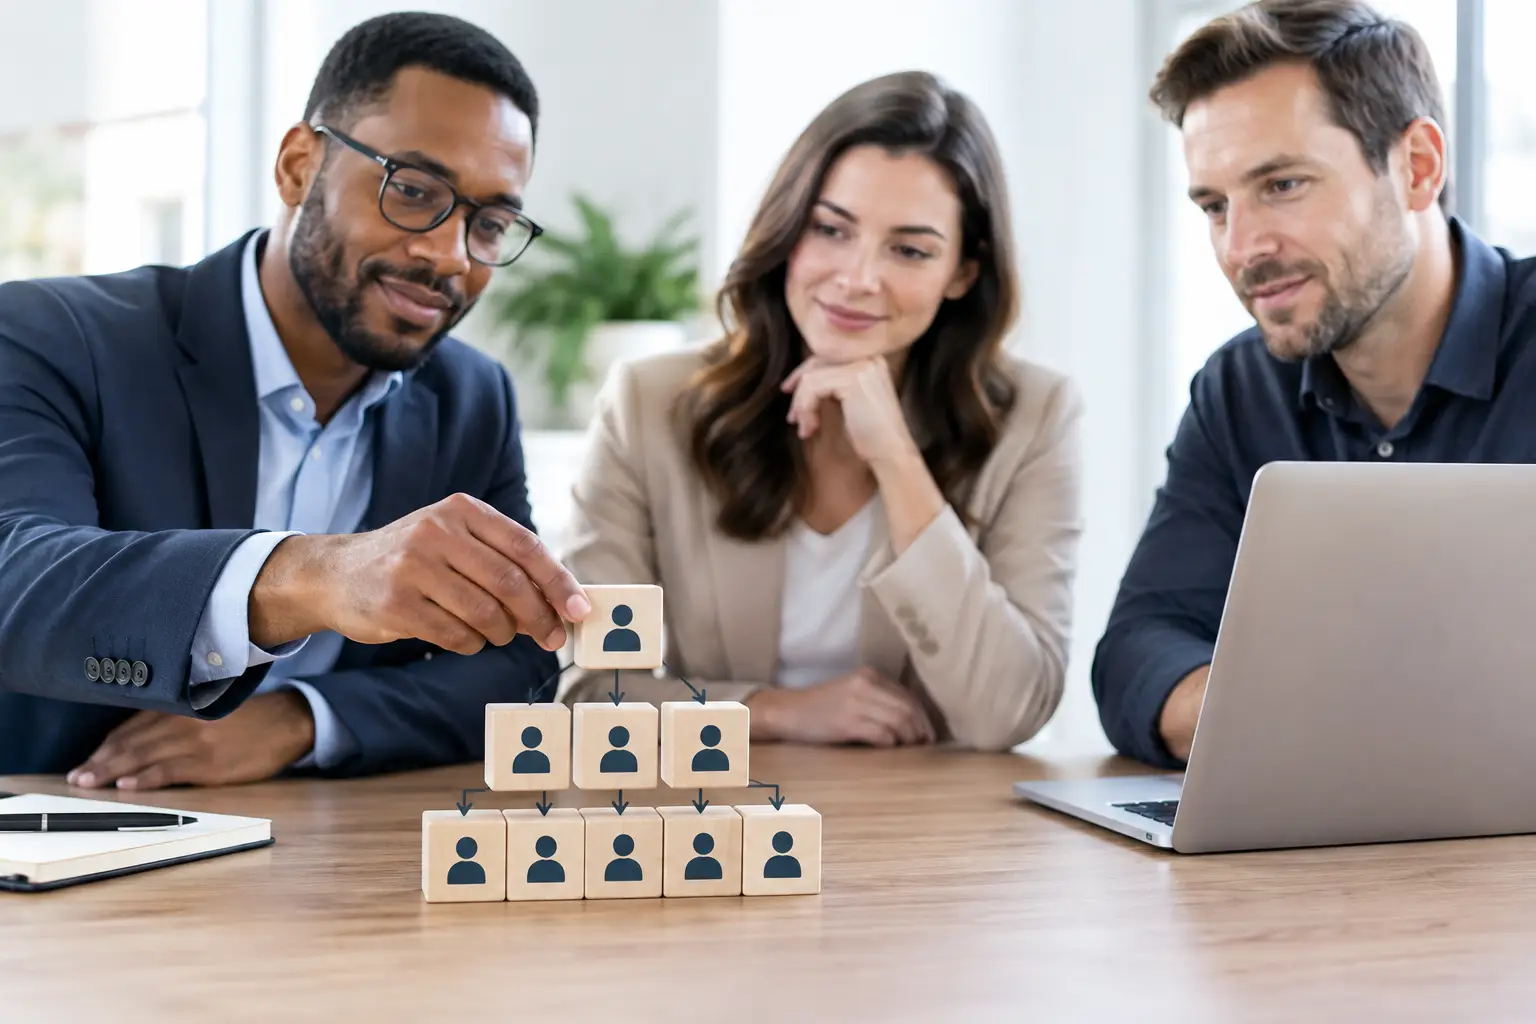
A useful approval structure separates authority from access. Access determines what a user can see or enter. Approval authority determines what they can authorize, under which conditions, and up to what dollar amount. An accounts payable clerk may need access to enter a bill, for example, without authority to approve it for payment. A warehouse lead may receive inventory without being able to approve the original purchase order.
Roles should reflect the risk of the action. Ordering standard parts under an approved budget carries a different level of exposure than issuing a customer credit, changing payroll information, writing off inventory, or approving a project overrun. Treating each action the same either creates unnecessary friction or leaves expensive gaps.
How to Set Up Approval Roles Around Real Workflows
Start with the workflows where a bad decision, missed review, or delayed approval has a measurable operational cost. For a field service contractor, that may be purchasing, job cost changes, timesheet exceptions, customer credits, and payment releases. For a distributor, inventory adjustments, vendor pricing changes, sales discounts, and returns may require tighter oversight.
Do not map every possible process on day one. Begin with the transactions that move money, commit inventory, alter financial records, or create obligations to customers and vendors. A practical first scope usually includes purchase requests, purchase orders, vendor bills, customer credits, expense reimbursements, payment runs, and material inventory adjustments.
For each workflow, document four decisions in plain language: who can submit it, who reviews it, what conditions require escalation, and what happens if the approver is unavailable. This forces the team to turn informal habits into a rule that can be applied consistently.
Use thresholds that match business risk
Dollar thresholds are the foundation of most approval structures, but they should not be the only trigger. A $500 order from an approved supplier for stocked material may be routine. A $500 order from a new supplier paid by wire transfer may deserve additional review.
Set approval limits by role, not by individual wherever possible. A purchasing coordinator might approve routine purchase orders up to $1,000 within an approved vendor and cost category. A department manager could approve up to $5,000. Larger commitments may require an operations leader or owner approval. The exact numbers depend on cash flow, average order value, and the cost of a purchasing error.
Use conditional rules for higher-risk situations. Escalation can be required when a purchase exceeds budget, a discount drops below a minimum margin, a vendor is new, a job is already over budget, an inventory adjustment exceeds a defined quantity, or a customer credit is issued after invoicing. These rules protect the business without forcing leadership to review every routine transaction.
Separate request, approval, receipt, and payment
A strong control structure avoids giving one person end-to-end authority over a transaction. This is often called separation of duties, but the operational logic is straightforward: no individual should be able to create a commitment and complete the financial outcome without review.
Consider a typical material purchase. A project manager requests materials for a job. A purchasing role creates the purchase order. A manager approves it if it exceeds the standard threshold or falls outside the job budget. Warehouse or field personnel confirm receipt. Accounts payable matches the vendor bill against the approved order and receipt before payment is released.
Not every business has enough staff to assign each stage to a different person. In a smaller company, compensating controls may be more realistic. The owner might review weekly payment reports, vendor changes, and exceptions above a set threshold. What matters is that the process makes improper or accidental activity visible before it becomes a loss.
Build an Approval Matrix People Can Follow
An approval matrix is the operating reference behind your system rules. It should be short enough for managers to use and precise enough for accounting and operations to configure consistently. Avoid vague language such as “management approval required.” Name the role, threshold, condition, and backup path.
A workable matrix should identify at least these elements:
- The transaction or change being requested, such as a purchase order, customer credit, time correction, or inventory write-off.
- The submitting role and the information required before it can be reviewed.
- The primary approver, approval limit, and conditions that trigger a higher level of review.
- The backup approver and the rules for delegated authority.
- The documentation required, such as a vendor quote, job number, receipt, customer communication, or reason code.
- The audit record that must be retained, including who approved, when they approved, and what was changed afterward.
Keep the matrix aligned with your chart of accounts, departments, locations, projects, and inventory categories. An approval rule that ignores job cost or department budget may approve spending that looks reasonable in isolation but damages profitability at the operating level.
Design for Exceptions Before They Become Emergencies
Approval processes often fail at the edges: a weekend service call, an unavailable manager, an urgent replacement part, or a customer dispute that needs immediate resolution. If the only answer is “call the owner,” the process will be bypassed when pressure rises.
Define emergency authority carefully. A service manager may be allowed to approve an urgent purchase above their normal limit when equipment downtime creates a larger cost than the purchase itself. That exception should require a reason code, supporting documentation, and follow-up review within a defined period. It is not a blank check.
Delegation needs the same discipline. Temporary approval rights should have a start date, end date, clear scope, and recorded owner. Permanent shared credentials are not delegation. They eliminate accountability and make audit trails unreliable.
Also decide what happens when an approver rejects or returns an item. The requester should see the reason, correct the issue, and resubmit without creating duplicate transactions. Clear statuses prevent staff from calling accounting to ask whether a bill, order, or credit is “stuck somewhere.”
Automate Routing, Not Judgment
A connected business platform can route a request based on department, location, project, transaction type, vendor status, and amount. That removes the manual chasing that causes approval delays across disconnected systems. It also creates one record of the request, its supporting documents, the decision, and the downstream financial impact.
Automation should handle predictable routing and reminders. It should not replace management judgment in unusual cases. A system can recognize that a project purchase exceeds budget. The approver still needs to decide whether the overage protects a customer relationship, prevents downtime, or signals a margin problem that needs a different response.
The same principle applies to notifications. Escalate overdue approvals based on business urgency, not merely elapsed time. A purchase order tied to tomorrow’s installation should move faster than a routine office supply request. Prioritization keeps controls from becoming an excuse for missed commitments.
Test the Rules Against Daily Operations
Before making approval roles mandatory, test them with real scenarios from each department. Run a standard replenishment order, an emergency field purchase, a disputed invoice, a customer credit, a payroll adjustment, and an inventory discrepancy. Confirm that each request reaches the correct person, that the approver sees enough context to decide, and that the final record is traceable.
Pay close attention to what happens after approval. If a purchase order can be changed materially without renewed approval, the original control has little value. If a vendor’s bank information can be edited immediately before payment, payment approval may not protect cash. Material edits should trigger a new review when they change amount, supplier, account coding, project allocation, quantity, or payment details.
Review your approval matrix quarterly and whenever responsibilities change. Growth, new locations, seasonal staffing, and new service lines can quickly make old approval limits irrelevant. Track approval time, rejection reasons, exception frequency, and transactions changed after approval. Those measures show where the workflow needs adjustment.
The best approval structure is rarely the strictest one. It is the one your team can follow under normal pressure, that flags meaningful risk early, and that leaves a reliable record when someone needs to understand why a decision was made.